.jpg)
.jpg)
 English daily published in Bengaluru & Doha
Rise of the financially confident Indian woman
For decades, financial planning in Indian households followed a predictable pat- tern. Men managed investments, while women often played a supportive role in budgeting and saving. That narrative is quietly but decisively changing. This shift represents more than financial participation. It reflects a deeper transformation in priorities, aware- ness, and confidence. Traditionally, women’s financial goals were closely tied to family responsibilities.
Typical priorities included: Saving for own wedding, children’s education and marriages, building family security through fixed deposits and gold, and supporting household financial stability. Today’s generation of women is expanding that list. While family responsibilities remain central, new financial priorities have emerged — including career advancement, financial independence, retire- ment planning for themselves, and personal aspirations such as travel and entrepreneur- ship.
This evolution reflects a fundamental shift: women are no longer just managing money — they are defining what money should achieve. Recent studies highlight this transformation. Nearly 47% of Indian women now take finan- cial decisions independently, and an overwhel- ming 98% of urban women participate actively in household financial decisions. Historically, gold and fixed deposits dominated women’s savings habits. These instruments offered security and familiarity.
However, the new generation of inves- tors is exploring broader opportun- ities. Women are increasingly investing in: Mutual funds, equities, debt instruments, and Systematic investment plans (SIPs). Data from capital markets shows that women now account for a growing share of retail inves- tors. One in four investors on the National Stock Exchange is a woman, and the number of women participating in mutual funds con- tinues to rise steadily. The mindset is shifting from saving to investing. Perhaps the most significant shift is in retire- ment planning. In the past, many women depended on their spouse’s retirement planning or family assets.
Today, women increasingly recognise the importance of planning retirement for themselves. However, awareness still needs to translate into deeper action. Studies show that only around 39% of women believe their retirement savings will last more than a decade. This highlights both progress and the need for continued financial education. Financial empowerment is also being driven by changing career paths. More women are pursuing higher education, leadership roles, and entrepreneurial ventures.
With this comes greater control over income and financial decisions. Career advancement, upskilling, and business opportunities are now appearing on women’s financial priority lists — some- thing rarely seen a generation ago. Financial independence is no longer a distant aspiration. It is becoming a practical objective. Cultural shift Interestingly, the rise of financially confident women is not just changing women’s lives. It is reshaping household dynamics as well.
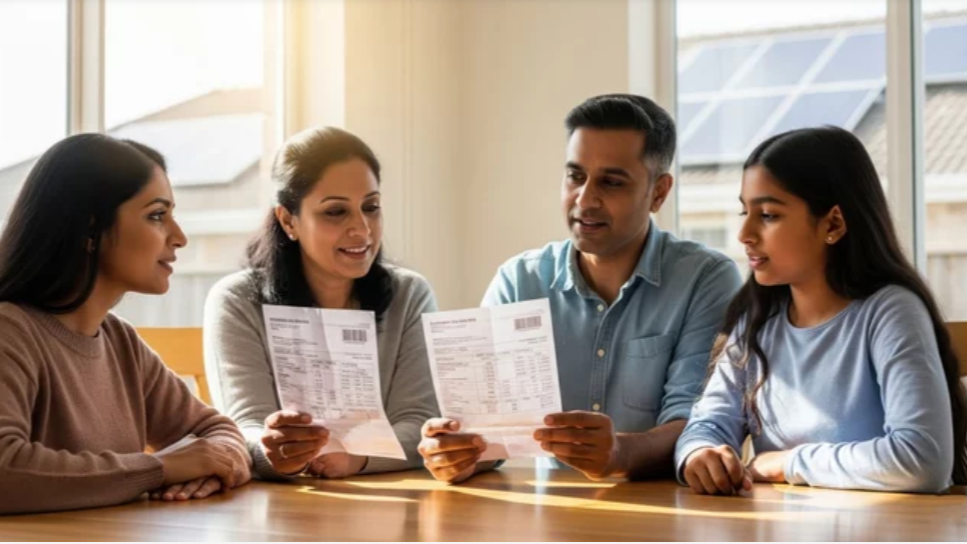
Couples are discussing investments together. Families are planning goals collectively. Children are growing up in households where financial lit- eracy is shared. This collaborative approach often leads to more balanced decision-making and stronger long-term planning.
.jpg)
.jpg)
.jpg)
.jpg)
.jpg)
.jpg)